Fiberglass Pipe Market Trends Shaping Oil and Gas Project Supply
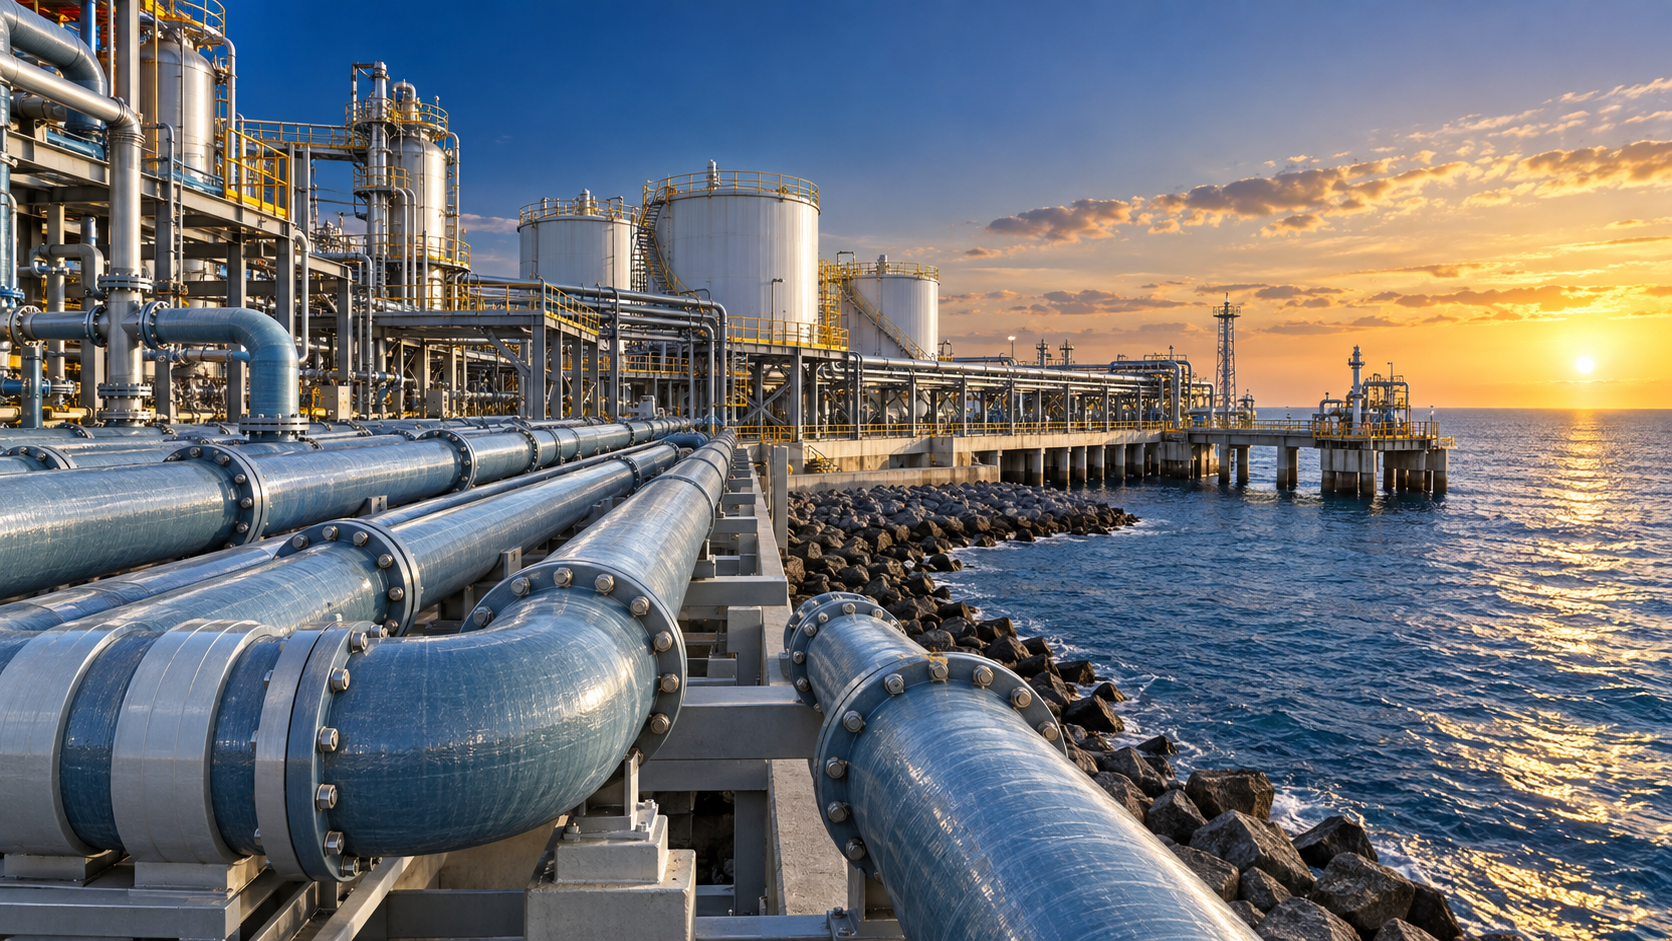
Oil and gas piping decisions are being reshaped less by a simple choice between metallic and non-metallic materials than by a broader supply question: can the selected system maintain integrity, schedule certainty, and predictable operating cost in a corrosive service environment? Fiberglass pipe—particularly fiberglass reinforced epoxy (GRE) systems—has gained strategic relevance where internal corrosion, external exposure, weight restrictions, or difficult installation conditions make conventional carbon steel costly to protect and maintain.
The important market shift is not that fiberglass pipe can replace steel everywhere. It cannot. Pressure regime, temperature, fire exposure, mechanical loading, permeation risk, joining requirements, and governing specifications still define its viable use. The more consequential change is that project teams are increasingly assessing composite pipe as a system with its own supply-chain, qualification, inspection, and lifecycle requirements rather than treating it as a secondary material option.
Corrosion cost is moving from a maintenance issue to an early supply decision
For produced water, seawater, firewater, utility water, chemical transfer, offshore service lines, and certain low- to medium-pressure hydrocarbon-related applications, corrosion is not merely an operational inconvenience. It affects material selection, coating scope, inspection planning, spare-parts strategy, shutdown exposure, and the total amount of construction work required on site.
Carbon steel remains a practical and often necessary choice for demanding high-pressure, high-temperature, structurally loaded, or fire-critical duties. Yet in corrosive fluid systems, its apparent purchase-price advantage can be weakened by internal linings, external coatings, corrosion allowance, cathodic protection interfaces, welding labor, and future repair activity. Stainless alloys can address many corrosion concerns but may introduce a different cost and availability profile. This has created a clearer commercial space for GRE and related fiberglass pipe systems where corrosion resistance is inherent to the laminate design rather than dependent primarily on a field-applied protective layer.
That distinction changes how supply is evaluated. A buyer is no longer comparing pipe price per meter alone. The relevant comparison may include fittings, joining method, installation productivity, transport weight, support design, inspection requirements, expected repair exposure, and the cost of managing corrosion over the operating period. Fiberglass pipe is therefore entering more early-stage engineering discussions, especially when the process fluid is known to be aggressive and the service envelope fits the composite system’s design limits.
The market is becoming more specification-driven
As composite pipe becomes more visible in oil and gas project packages, generic descriptions such as “FRP pipe” or “corrosion-resistant fiberglass pipe” are insufficient for commercial evaluation. Resin chemistry, reinforcement architecture, liner construction, winding process, pressure class, temperature capability, joint configuration, and testing regime can materially affect performance.
GRE pipe is not a single interchangeable product category. Epoxy resin systems are commonly selected for their chemical resistance and mechanical performance, but suitability still depends on the actual fluid composition, operating temperature, pressure fluctuations, solids content, cleaning chemicals, and possible upset conditions. A line designed for treated water may not be appropriate for a chemically variable effluent. A system suitable for continuous service at one temperature may require derating or a different laminate design when exposed to higher temperatures or thermal cycling.
This is driving a stronger emphasis on project-specific documentation. Commercial offers increasingly need to demonstrate not only nominal dimensions and pressure ratings, but also the design basis behind them. Buyers should expect clarity on design pressure versus operating pressure, temperature limits, safety factors, vacuum capability where relevant, allowable external loads, joint pressure rating, and chemical-service assumptions. A supplier that cannot connect its product data to the actual duty conditions creates uncertainty that will surface later during engineering review or site installation.
Standards also matter, but they should not be used as a substitute for application review. Depending on the service and project specification, composite piping may be assessed against standards such as ISO 14692 for petroleum and natural gas industries, ASTM product and test methods, or owner-specific requirements. Compliance claims need to be read carefully: a reference to a standard does not automatically establish that every pipe, fitting, joint, and installation practice is qualified for the proposed service. The relevant question is whether the offered system has been designed, manufactured, and documented against the applicable project requirements.
Manufacturing capacity matters only when it is usable capacity
Oil and gas projects frequently underestimate the difference between nominal factory capacity and deliverable capacity. A manufacturer may have substantial winding equipment, but a project’s actual supply risk depends on whether the facility can produce the required diameters, pressure classes, fittings, bends, flanges, reducers, and custom spools within the required quality-control window.
Fiberglass pipe production is particularly dependent on process consistency. Filament winding tension, resin mixing and wet-out, curing conditions, laminate thickness control, liner formation, dimensional accuracy, and fitting fabrication all influence the finished system. Capacity should therefore be assessed alongside process control, not in isolation.
A commercially useful supplier review should distinguish among several questions:
- Whether pipe and fittings are manufactured under the same controlled system or sourced from different parties.
- Whether the production line can accommodate the required diameter range and pressure class without exceptional setup risk.
- Whether hydrostatic testing, dimensional inspection, cure verification, and traceability records are available for the relevant products.
- Whether fabrication capacity is balanced across straight pipe, fittings, and project-specific accessories.
- Whether the supplier can manage batch identification and documentation through packing and shipment.
Fittings deserve special attention. Straight pipe is often the simplest part of a composite package to scale. Fittings, however, can become the schedule constraint because they involve more varied molds, winding operations, machining, bonding, or finishing steps. A supply proposal that looks competitive based on pipe volume may prove less reliable if the fitting schedule has not been examined in equal detail.
Factory test capability is another market differentiator. Static hydrostatic testing machines, for example, support routine pressure verification, but their value depends on how they are integrated into the quality system. Buyers should seek evidence of test scope, acceptance criteria, calibration control, record retention, and the relationship between production batches and test records. Testing should confirm a controlled manufacturing process; it should not be treated as a last-minute remedy for an uncontrolled one.
Global sourcing is expanding, while qualification remains local to the project
Composite pipe suppliers now serve projects across a wider range of manufacturing and installation geographies. This can improve sourcing options, especially where domestic supply is limited or where project owners seek alternatives to a narrow supplier base. It also makes supplier qualification more demanding. Export experience alone does not demonstrate readiness for a specific project.
International supply reliability rests on practical details: packaging that prevents ultraviolet exposure or transport damage where applicable; clear marking; compatibility between pipe lengths and container loading; preservation of joint surfaces; availability of installation consumables; document control in the required language; and the ability to resolve technical queries across time zones. For adhesive-bonded or mechanically joined systems, the availability and shelf-life management of joining materials can be as important as the pipe shipment itself.
Logistics can also alter the apparent advantage of low-weight pipe. Fiberglass systems are lighter than comparable steel systems, which can reduce handling demands and may benefit offshore, remote, or constrained sites. However, long pipe lengths, large diameters, specialized packing, and the need to avoid point loading still require disciplined transport planning. The commercial benefit comes from optimizing the full package, not simply from comparing freight weight.
Supply diversification is valuable only when technical equivalence is maintained. Requalifying an alternative fiberglass pipe source late in a project can introduce delay if drawings, fittings, joint methods, or supporting systems differ. A better approach is to define the critical equivalence criteria at the procurement stage: resin family, laminate design basis, pressure-temperature envelope, joint type, qualification documents, dimensional interfaces, and inspection requirements. This prevents “approved alternative” from becoming a vague designation with hidden engineering consequences.
Installation competence is becoming part of the material decision
The market increasingly treats fiberglass pipe as a supplied system rather than a delivered product. This is justified. A correctly manufactured pipe can still fail prematurely if it is cut improperly, joined outside the prescribed cure conditions, supported at unsuitable spacing, subjected to excessive bolt torque, or installed with misalignment and uncontrolled loads.
Jointing is central to this issue. Depending on the system design, GRE pipe may use adhesive-bonded joints, mechanical couplings, flanged connections, threaded connections in limited applications, or other proprietary arrangements. Each method has specific requirements for surface preparation, fit-up, adhesive use, cure time, torque, and inspection. A project schedule that assumes the same field workflow as welded steel pipe may be unrealistic. The crew’s training, environmental conditions, access to tools, and inspection hold points need to be incorporated into construction planning.
Support design also requires attention. Fiberglass has different stiffness, thermal expansion behavior, and load response from steel. Poorly spaced supports, unsupported valves, excessive concentrated loads, or inadequate guides can create stresses not visible in a simple line-item procurement comparison. The commercial implication is straightforward: a lower material price does not compensate for incomplete engineering of supports, interfaces, and installation procedures.
This is particularly relevant in mixed-material systems. Steel-to-GRE connections need careful consideration of flange alignment, support transitions, differential movement, galvanic conditions where metallic elements are involved, and the transfer of loads from heavy equipment. The strongest supply packages provide installation manuals, jointing procedures, training provisions where required, and clear limitations on field modifications.
LNG, offshore and chemical service are refining demand rather than creating a universal replacement market
The most credible expansion areas for fiberglass pipe are those where its attributes directly address a defined project problem. Offshore utility and seawater lines value corrosion resistance and reduced weight. Produced-water and water-injection-related systems may value resistance to corrosive aqueous media, subject to fluid chemistry and pressure requirements. LNG-associated facilities can use composite piping in selected utility or process-support services, but low-temperature conditions require explicit confirmation of material suitability rather than broad assumptions. Chemical processing environments similarly demand a resin-and-liner review against the actual chemicals, concentration, temperature, and cleaning regime.
That is why sector labels alone are inadequate. “Oil and gas,” “LNG,” and “chemical plant” describe operating environments, not final material specifications. A fiberglass system suited to a Chemical Plant utility line cannot automatically be transferred to a hydrocarbon-bearing process line, and a marine ballast application does not establish suitability for hot chemical effluent. The trend is toward narrower but better-defined use cases, supported by service-specific engineering evidence.
Fire performance is an additional boundary condition that should not be overlooked. Composite pipe can be designed with fire-resistant features for certain applications, but fire endurance, smoke generation, flame spread, and post-fire integrity requirements vary by project and location. It is risky to treat “fire-resistant” as a universal category. The required test basis and acceptance criteria should be established before material selection, particularly for offshore installations and safety-critical systems.
Lifecycle analysis is becoming more disciplined
Fiberglass pipe is often presented as a lifecycle-cost solution, but the claim is only meaningful when the analysis includes the conditions that drive lifecycle value. These can include corrosion mitigation avoided, installation labor, lifting requirements, coating or lining scope, inspection burden, shutdown consequences, replacement intervals, and expected fluid-service stability. They can also include costs that are sometimes omitted: engineering review, installation training, specialty tools, spare fittings, field jointing controls, and potential repair capability.
A robust comparison does not assume that composite is always lower cost over time. In a short-duration project with readily available steel, benign fluid service, high mechanical exposure, or demanding thermal requirements, conventional metallic pipe may remain the more rational choice. Conversely, in a remote corrosive-water system where future access is expensive, the economics can shift substantially even if the fiberglass package has a higher initial procurement cost.
The key market trend is therefore a move away from generic “lightweight and corrosion-resistant” claims toward duty-specific economic evaluation. This favors suppliers able to provide technical documentation that supports commercial modelling, and it favors buyers that involve engineering before commercial terms are finalized.
What will determine supplier credibility
Supplier selection is likely to depend increasingly on evidence that the pipe system can be delivered as specified, not merely on whether a factory can manufacture fiberglass products. Credibility is strengthened by transparent manufacturing scope, controlled testing, traceable materials, documented qualification, responsive engineering support, and a realistic account of installation requirements.
For project supply teams, the most useful questions are often the least promotional: What exact service envelope has been assumed? Which components are made in-house? How are fittings qualified? What records accompany each shipment? What jointing materials and procedures are required? What happens if a field modification is needed? Which interfaces remain the contractor’s responsibility?
Fiberglass pipe is becoming a more consequential part of oil and gas supply strategy because it can solve real corrosion, weight, and constructability problems in the right service. Its market direction will be shaped not by broad substitution claims, but by the ability of manufacturers, engineers, and project buyers to define those services precisely—and to manage the composite system from design release through installation and operation.
Please give us a message
产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍
Please give us a message
产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍
Please give us a message
产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍
Please give us a message
产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍产品介绍